Thailand’s Securities and Exchange Commission has proposed a same-owner requirement for stablecoin transfers that would sharply narrow how customers can move tokens such as USDT through licensed crypto firms. The measure remains at the consultation stage and is not yet an operative rule.
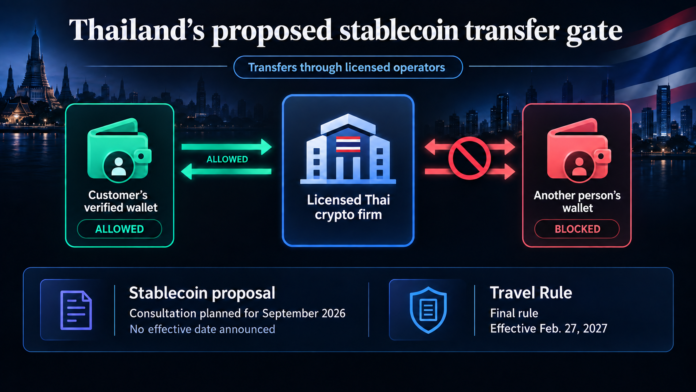
Under the SEC Board-approved Sept. 3 consultation principles, stablecoins entering a customer account at a digital asset operator would have to come from an account or wallet verified as belonging to that customer. Withdrawals would likewise have to go to an account or wallet verified as the customer’s own.
The consequence is explicit: a stablecoin deposit from another person’s account, or a withdrawal to another person’s account, would be prohibited.
How the proposed ownership gate would work
As drafted, the restriction would stop a customer from using a Thai SEC-supervised platform to receive a transfer from someone else’s wallet or to send stablecoins to another person’s wallet. Its reach is limited to transfers conducted through supervised digital asset operators, rather than peer-to-peer transfers that take place entirely outside those firms.
The proposal would also require stablecoin transfer values to be consistent with a customer’s income source and financial position. Inbound and outbound transfers would each be capped at 5 million baht per day, per person, per operator.
The cap would not apply to transfers between customer accounts through SEC-supervised operators when both firms comply with the Travel Rule. The Sept. 11 consultation also lists cap exemptions for specified operator business transfers, certain Bank of Thailand-authorized operators and stablecoin/baht market makers. It remains unclear whether that cap waiver would affect the separately stated same-owner test, and consultation could add implementation detail.
The SEC said it developed the measures after observing significant growth in stablecoin transaction volume and value, particularly involving USDT. It also cited patterns that it associated with risks tied to money laundering, cybercrime and the circumvention of rules governing international money transfers.
The ownership test would be separate from Thailand’s finalized Travel Rule. That rule requires digital asset operators to collect information about transfer parties, check counterparties and verify ownership or control of certain self-hosted wallets. It takes effect on Feb. 27, 2027.
As described, the stablecoin proposal would add a stricter condition when a transfer crosses the boundary of a licensed operator: the outside sending or receiving account would have to belong to the platform’s customer, not another person.
On Sept. 11, the SEC opened the public consultation, with comments due by Sept. 25, 2026. It did not announce an effective date for the proposed stablecoin restrictions. Until final rules are issued, the same-owner restriction remains a proposal.