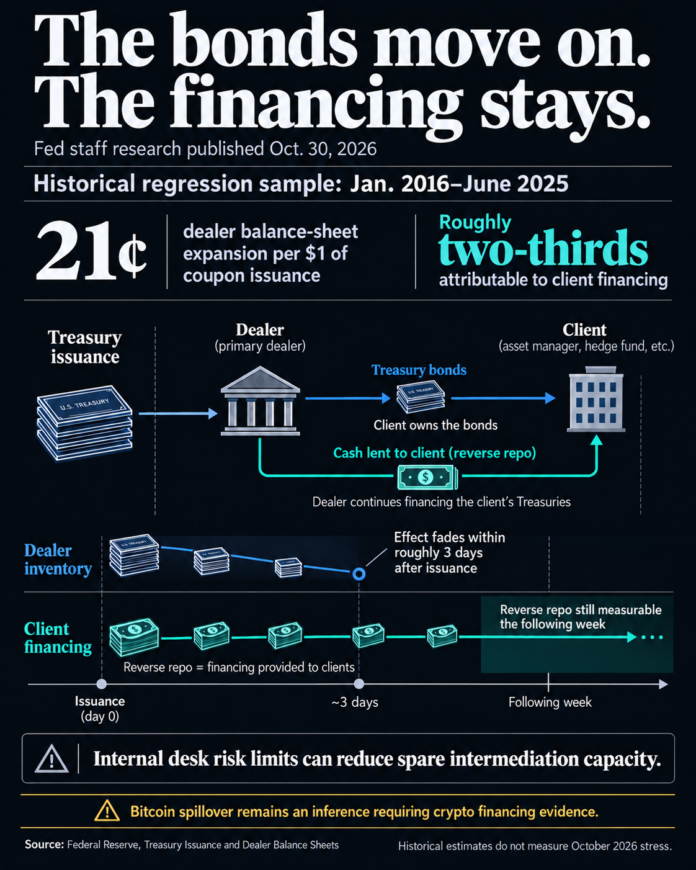
Federal Reserve staff research published Oct. 30 finds that Treasury dealers can keep financing customers’ bonds after their own auction inventory has largely cleared. That lingering lending uses balance-sheet capacity, so falling inventories can give an incomplete picture of dealers’ ability to finance Treasury positions.
The study estimates that each dollar of Treasury coupon issuance expanded dealer balance sheets by about 21 cents, with roughly two-thirds attributable to client financing. Its main regression sample covers eight large bank-affiliated dealers from January 2016 through June 2025. These are historical estimates, rather than measurements of October 2026 stress.
The mechanism separates owning a bond from financing its owner. Dealers can sell Treasuries to customers while continuing to supply repo financing, short-term loans secured by the bonds. As the New York Fed explains, dealers also borrow cash to fund their lending to leveraged clients. Moving the security off inventory need not end that intermediary role.
In the Fed study, the effect of coupon issuance on dealers’ long positions dissipates within roughly three days after issuance. The increase in reverse repo, the financing dealers provide clients, remains measurable during the following week.
The study associates issuance with greater use of Treasury trading desks’ internal risk limits, which can reduce spare intermediation capacity. Its illustrative leverage-ratio calculations, however, put temporary issuance effects well below aggregate regulatory headroom. Available room across dealers does not establish spare capacity at each desk.
New York Fed observations put the Secured Overnight Financing Rate, or SOFR, between 3.92% and 3.95% across the five business days from Oct. 23 through Oct. 29. The latest reading in that window was 3.94%.
The Federal Home Loan Bank of New York’s Oct. 30 update cites a 3.90% interest rate on reserve balances and attributes SOFR trading above it to Treasury supply, month-end and Canadian year-end. Yet it also describes financing conditions as tranquil enough for the Fed’s reserve-management purchases to remain paused.
The missing link between Treasury dealers and Bitcoin
If the same constrained intermediaries fund Bitcoin traders, cuts in their lending could transmit Treasury pressure into crypto. That remains an inference about financing capacity, not an observed result of the Fed study. The Bank for International Settlements’ April 2023 Crypto carry research identifies scarce arbitrage capital and leveraged investor demand as drivers of the gap between futures and spot prices. It also finds some segmentation between crypto and traditional markets, with interest-rate differentials explaining little of carry variation.
Treasury repo rates measure secured borrowing costs. Futures basis measures a price gap. Perpetual funding, meanwhile, transfers payments between longs and shorts to anchor the contract to its index.
A stronger spillover case would pair persistent repo pressure with worsening comparable crypto borrowing or rollover terms. Establishing causation would require evidence connecting constrained intermediaries to reduced Bitcoin financing. Stable crypto credit terms would weaken the spillover explanation, even if Treasury financing remained expensive.